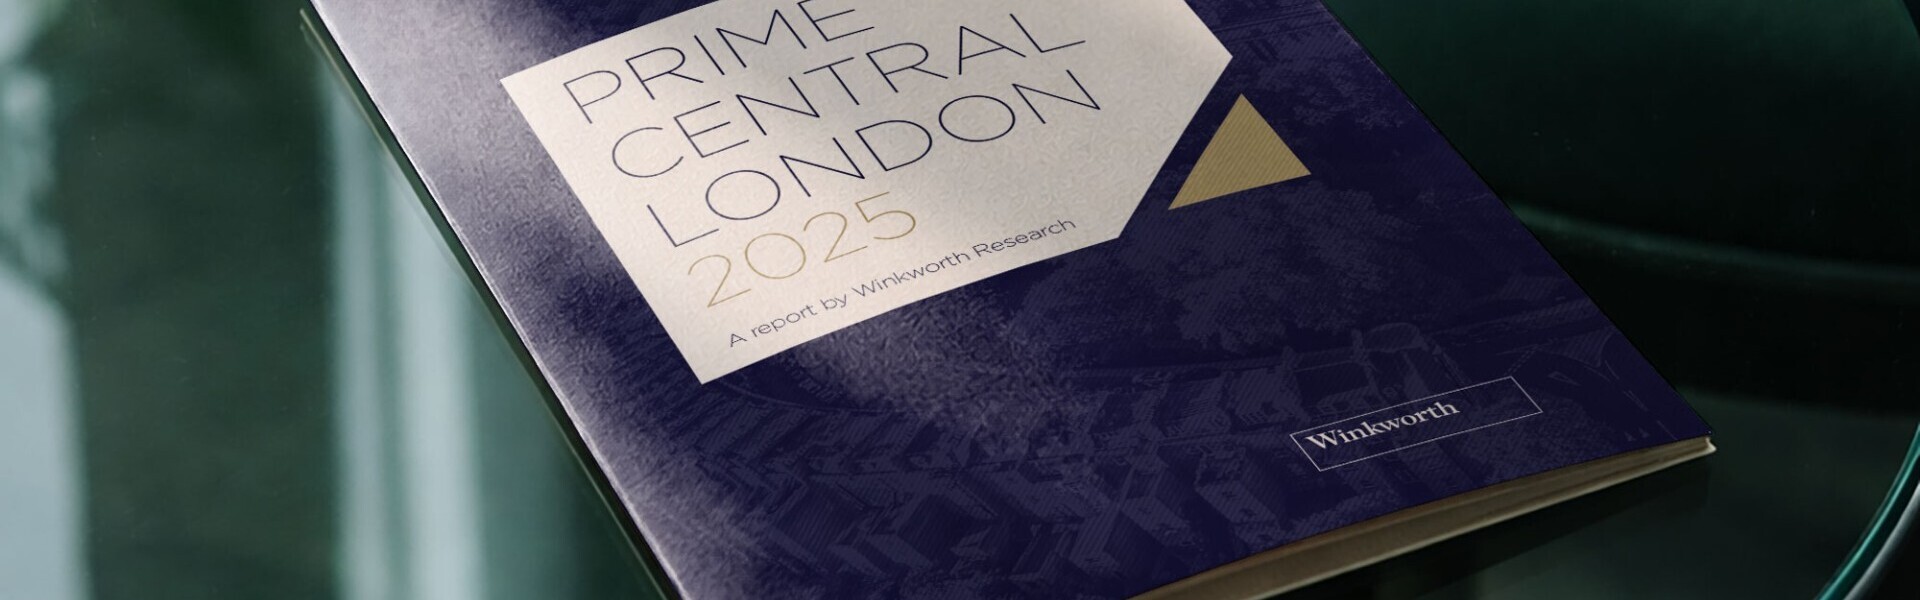
Covering established neighbourhoods including Kensington, Knightsbridge, Notting Hill, Pimlico and Paddington: our report explores how buyers, sellers and tenants are navigating a market adjusting to a new reality, defined by repriced expectations, needs-based demand, and structural change.
Sales activity in Q1 held essentially flat year-on-year, but only where pricing genuinely reset, with committed domestic buyers in the £2m to £3m range driving most activity. In lettings, tenant demand surged with applicants up 39%, though rents softened as tenants pushed back and landlord confidence wavered under the weight of incoming legislation. With interest rate expectations shifting and the High Value Council Tax Surcharge on the horizon, our spring update offers a grounded view of how Prime Central London is responding as we move through 2026.
[Add issue]